We compare Minnesota's top-rated insurance companies to find you strong coverage at a fair price. One local team handles your personal and business insurance.
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.
04
A propane heater left running overnight on Mille Lacs. A wheel house towed down Highway 169 with a loose safety chain. A skid house that sat one warm week too long on Upper Red Lake. Each of these scenarios ends with a phone call to an insurance agent, and too often the owner learns that the policy they assumed would pay out has a gap right where the loss happened.
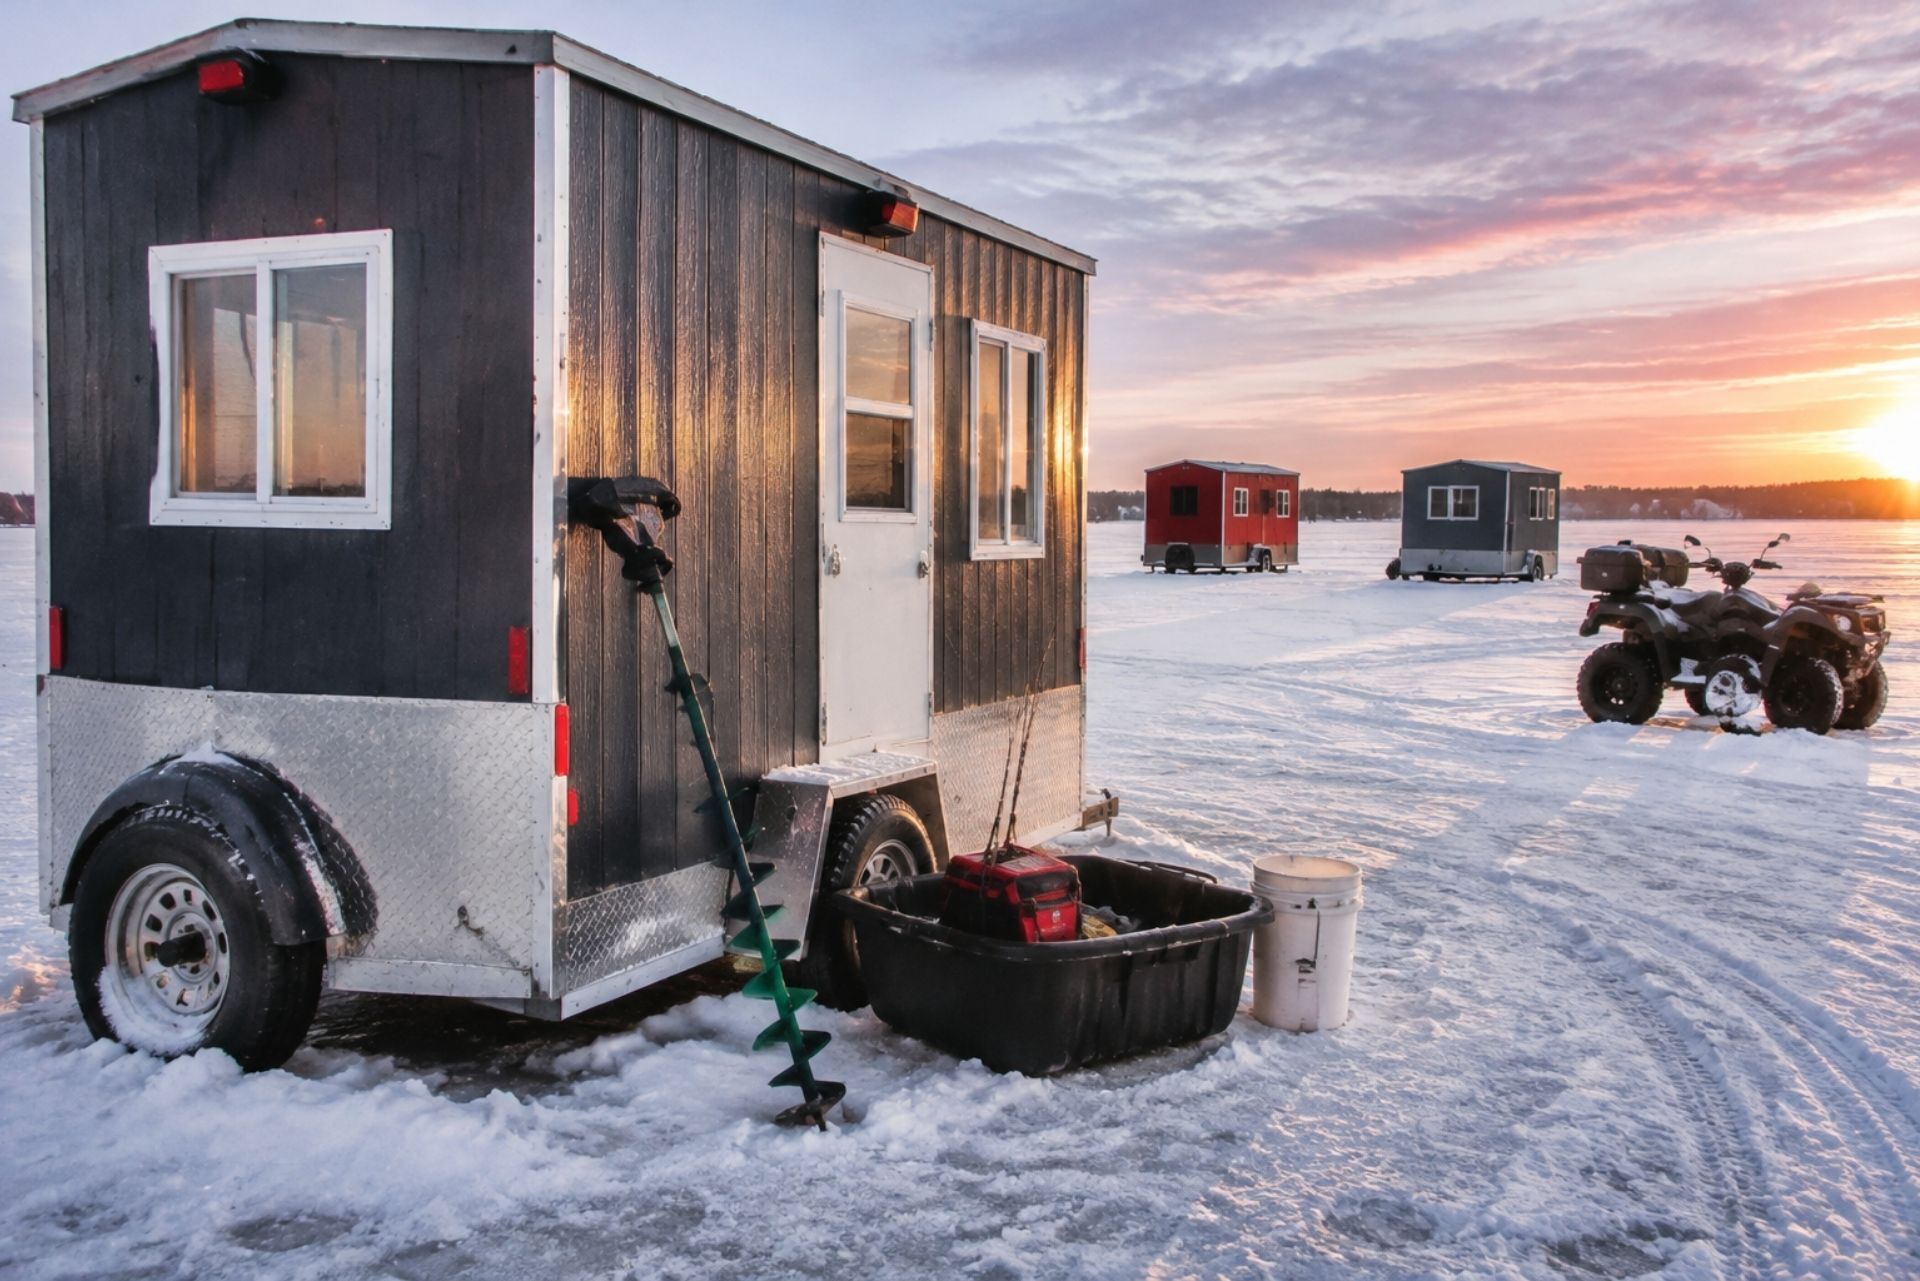
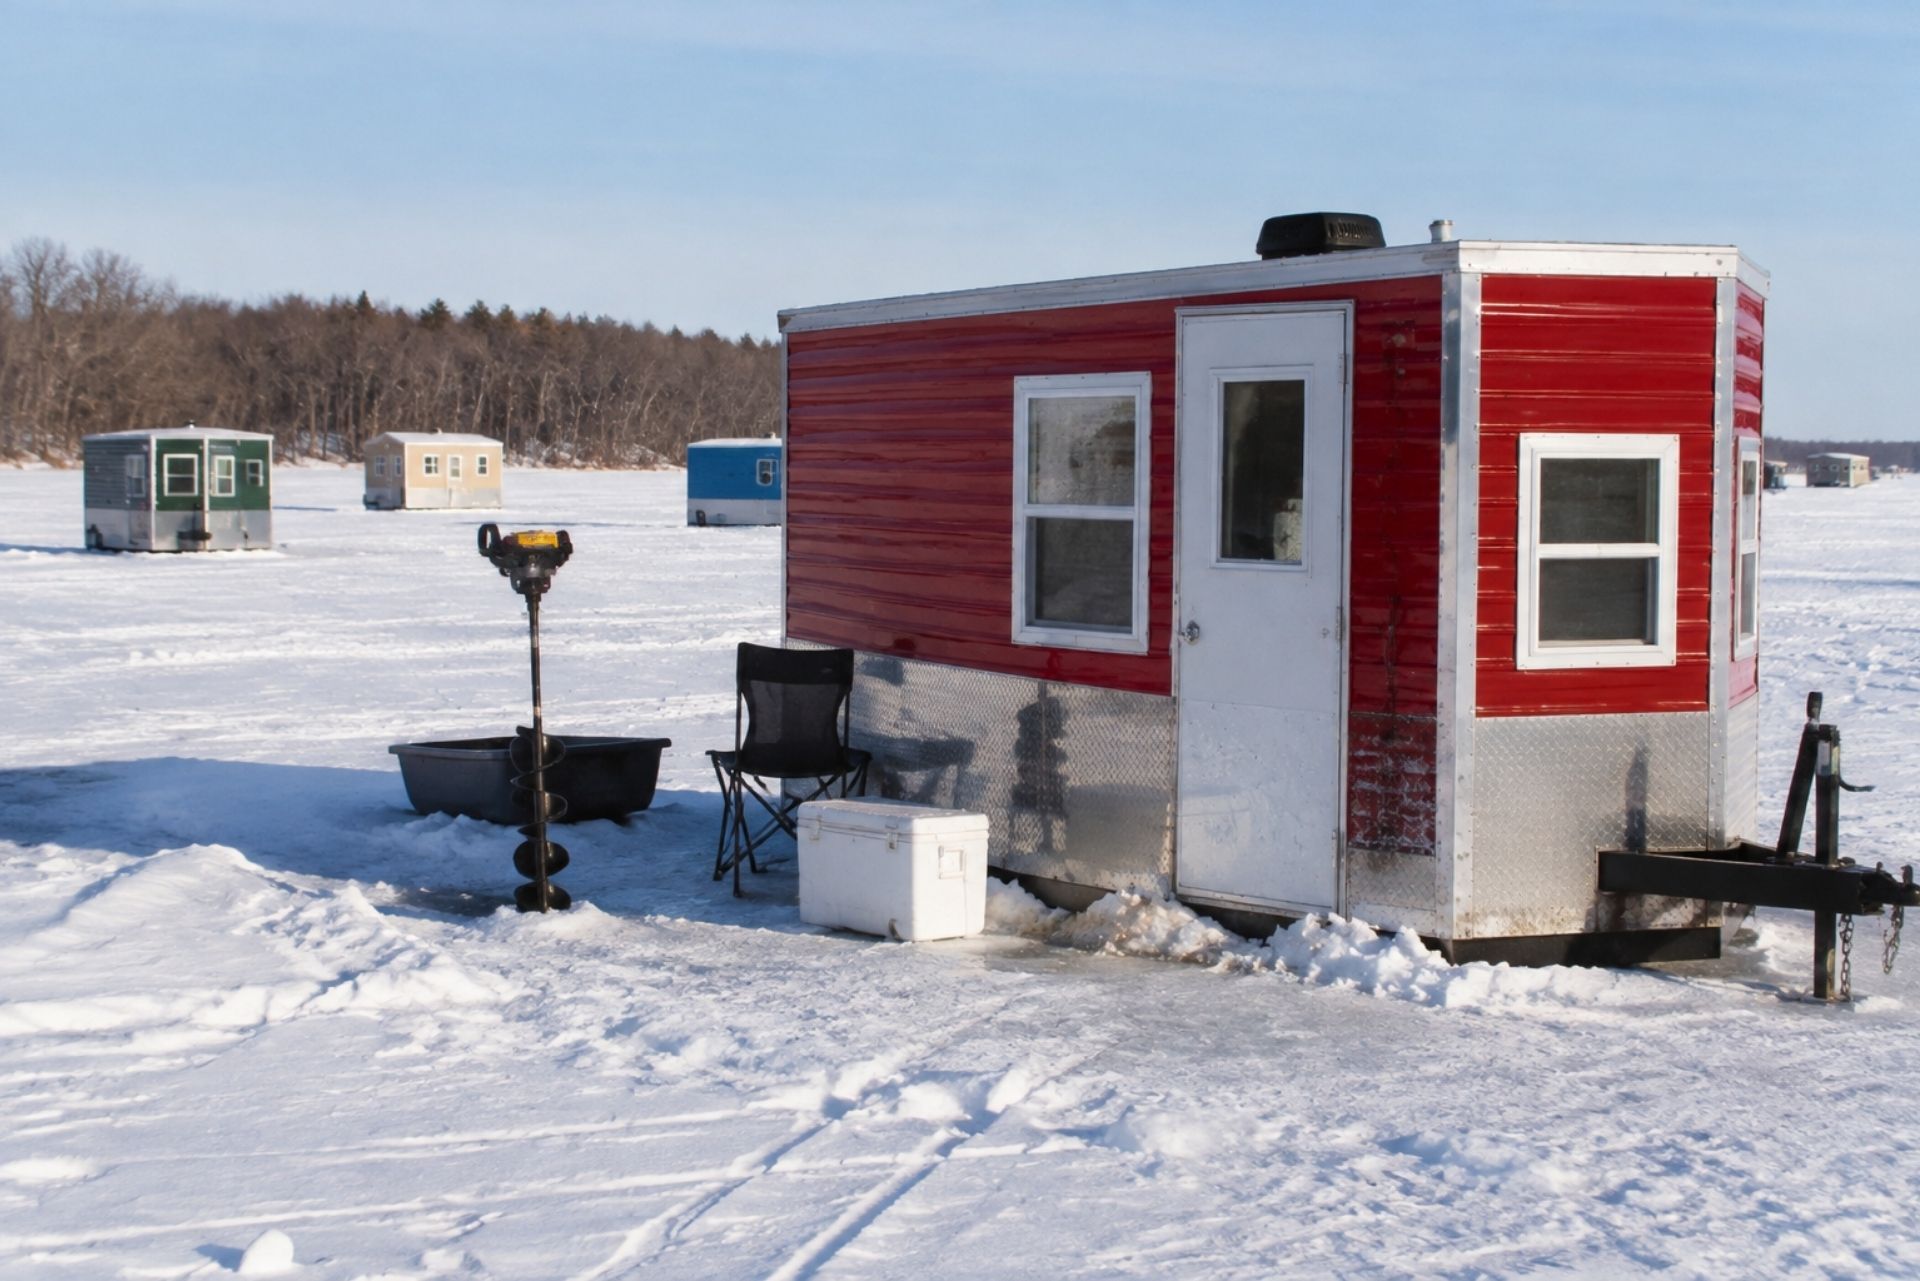
Fish houses have grown from plywood shacks into rigs that rival small cabins, with insulated walls, bunks, televisions, generators, and gear worth thousands on its own. Yet many Minnesota owners still insure them as an afterthought, or not at all. This guide walks through how Minnesota fish house and ice house insurance actually works: on-ice losses, fire and heater claims, theft, towing liability, contents, and what it all costs.
Protecting Your Minnesota Ice Fishing Investment
Here's the first thing to understand: there is no single "fish house policy" that every carrier writes the same way. Depending on how your house is built and how you use it, coverage might come from your homeowners policy, an RV or travel trailer policy, an inland marine policy, or a dedicated specialty fish house policy. Each one treats the ice differently, and the ice is where most claims happen.
Before insurance even enters the picture, the state has its own rules. All non-portable ice shelters in Minnesota must be licensed, and for the 2026-2027 season the annual shelter license runs $15 for residents and $37 for non-residents. A license keeps you legal with the DNR. It does nothing to protect your investment if the house burns, breaks through, or disappears from an access point.
The owners who get burned (sometimes literally) usually make one of three mistakes:
- Assuming homeowners covers it automatically. Some policies exclude structures that aren't on your residence premises, and a house parked on a lake miles away may not qualify.
- Insuring the shell but not the contents. Augers, flashers, cameras, and electronics add up fast.
- Forgetting the trip there and back. Towing creates liability exposure that a property policy won't touch.
Think of your rig as three separate risks: the structure, the stuff inside it, and the liability you carry while using and moving it. A good policy addresses all three.

Core Coverage: On-Ice Loss and Physical Damage
Physical damage coverage pays to repair or replace the house itself. On land, that usually means wind, hail, vandalism, collision with another object, and similar perils. Once the house sits on a frozen lake, the risk profile changes completely, and that's where policy wording starts to matter more than the price.
Pay close attention to whether your coverage is written on a named-perils or open-perils basis. Named perils covers only what's listed. Open perils covers everything except what's specifically excluded. With fish houses, the exclusions list is where you find out whether sinking, freezing to the ice, or damage from removal is actually covered.
Also ask whether the policy pays actual cash value or replacement cost. A five-year-old wheel house paid at actual cash value might leave you thousands short of buying a comparable rig at today's prices.
The Risk of Breakthrough and Submersion
Breakthrough claims are the ones that keep fish house owners up at night, and they're also the ones most likely to be excluded from a general policy. When a house goes through, the loss isn't just the structure. There's the recovery effort: divers, winches, specialized equipment, and sometimes environmental cleanup if fuel or batteries end up in the water.
Market data shows that specialty fish house policies commonly include ice recovery coverage, while many homeowners and RV policies don't mention it at all. If your policy is silent on recovery, assume you'll be paying for it yourself.
The DNR makes a point every owner should take to heart: a date is not a description of a surface. Legal removal deadlines tell you when the house must be off the ice, not when the ice is safe to hold it. Some carriers will scrutinize a late-season breakthrough claim, especially if the house was left out during an obvious thaw. Pulling early protects both your rig and your claim.
Fire Hazards and Propane Heater Safety
Fire is the other big on-ice loss. A small, sealed, heavily insulated space with propane heaters, cooking appliances, wiring, and fuel cylinders gives a fire everything it needs. Once a fish house fire starts on a lake, there's usually no fire department coming in time to save the structure.
Most property policies cover fire as a basic peril, so the question is less about whether fire is covered and more about what an adjuster finds when they investigate. Claims get complicated when the heater wasn't rated for indoor use, the propane setup was improvised, or the house was left with a heater running unattended. Carriers may also ask about carbon monoxide and smoke detectors.
A few habits make claims cleaner and fires less likely:
- Use heaters rated for enclosed spaces and follow the manufacturer's ventilation guidance.
- Store spare cylinders outside the living area and check connections every trip.
- Keep a fire extinguisher by the door and working CO detectors installed.
- Photograph your heating setup at the start of the season for your records.

Liability Risks: Towing and Guest Safety
Your fish house becomes a liability exposure the moment someone else steps inside. A buddy trips over an auger hole and breaks a wrist. A guest gets sick from carbon monoxide. A neighbor's truck clips your house parked on a plowed ice road. Each of these can turn into a claim against you.
Many homeowners policies extend personal liability to activities away from home, which can cover a guest injured in your fish house. That said, the coverage depends on how the house is classified. If your carrier considers it a trailer or vehicle, the homeowners liability may step aside in favor of auto or RV liability, and you don't want to discover the gap after a lawsuit lands.
If you rent your house out, even occasionally through a resort or a peer-to-peer listing, tell your agent. Rental use is a classic exclusion on personal policies, and it can void coverage for the entire loss, not just the rental-related portion.
Towing Liability and Over-the-Road Transit
Towing is where personal fish house coverage most often falls apart. When you pull a wheel house behind your truck, your auto policy's liability coverage generally extends to the trailer you're towing. Physical damage to the house itself is a different story. If you jackknife on an icy county road, your auto policy may pay for the other driver's car while your fish house damage goes uncovered.
Check these points before the first trip of the season:
- Liability follows the tow vehicle: confirm your auto liability limits are high enough for a heavy load.
- Physical damage to the house: needs its own coverage through a trailer, RV, or specialty policy.
- Contents in transit: gear rattling around inside may or may not be covered while moving.
- Lake roads and plowed ice paths: ask whether a collision on the ice counts as on-road or off-road.
Lighting, brakes, and safety chains matter for more than legal compliance. An adjuster reviewing a towing accident will look at them closely.
Securing Your Gear and Personal Contents
Ask a seasoned angler to list what's inside their house and you'll hear about flashers, underwater cameras, rods and reels, a generator, a TV and satellite setup, power augers, bedding, cookware, and a cooler full of food. Replacement cost for a well-equipped rig's contents can rival the value of an older shell.
Theft is a real risk. Houses left on popular lakes midweek are easy targets, and thieves know which access points have little traffic. Some policies treat theft from an unattended structure differently than theft from your home, and a few require visible signs of forced entry before they'll pay. Locks, hitch locks for wheel houses, and trail cameras all help, both as deterrents and as evidence.
Here's what that means for you: build a contents inventory before the season starts. Photograph each item, record serial numbers on electronics, and keep receipts in a cloud folder. When a claim comes in, the owners with a documented inventory get paid faster and more completely than those trying to remember what was in the cabinet.
Also check how contents are covered under your policy. Homeowners policies often cover personal property away from home at a reduced percentage of your total contents limit. Specialty fish house policies tend to include full contents coverage for the gear kept in the house, which is a big part of their appeal.
Comparing Policy Types and Coverage Limits
The right policy depends on what you own and how you use it. Here's a plain-language comparison of the three most common approaches:
| Feature | Homeowners (Scheduled Item) | RV / Trailer Policy | Specialty Fish House Policy |
|---|---|---|---|
| Structure coverage | Yes, at scheduled value | Yes | Yes |
| Ice recovery | Rarely included | Varies, often excluded | Commonly included |
| Contents | Often limited | Varies | Full contents typical |
| Towing physical damage | Often excluded | Usually included | Usually included |
| Separate deductible | Yes | Yes | Yes |
| Best fit | Smaller skid houses | Wheel houses used like campers | Higher-value rigs on the ice all season |
Adding a fish house to your homeowners policy as a scheduled item is the simplest option. You list a specific value and choose a deductible for it. It can work well for a modest skid house, but read the fine print on where the house is covered and whether submersion is excluded.
RV and trailer policies make sense for wheel houses that double as summer campers. They usually handle towing and physical damage well, though ice-specific losses can be a weak spot. Specialty policies are built for the ice, so they're the most complete option for owners with serious money tied up in a rig.
What Determines Your Minnesota Insurance Premium?
Specialty fish house policies typically cost between $250 and $600 per year, and that range generally includes ice recovery and full contents coverage. Where you land within it depends on several factors carriers weigh during underwriting.
The value of the house drives most of the cost. A newer, fully loaded rig costs more to insure than a basic shell. Your deductible choice, your claims history, the lakes you fish, how long the house stays on the ice, and whether you store it securely in the off-season all play a role too.
If you're scheduling the house on a homeowners policy instead, keep the bigger picture in mind. Minnesota homeowners rates rose by an average of 34% in 2025-2026, and since scheduled items ride on that base policy, owners who assumed the homeowners route was the bargain may want to compare it against a standalone option this year. Sometimes the cheaper path on paper costs more once you factor in exclusions.
Wheel House vs. Skid House Cost Factors
Wheel houses and skid houses carry different risks, and carriers price them accordingly. A wheel house spends time on the road, so towing exposure, collision, and theft from storage lots all come into play. These rigs also tend to be worth more, with finished interiors and built-in systems.
Skid houses usually stay on the ice for longer stretches and get moved less often. That reduces road risk but increases exposure to breakthrough, freezing in, and theft from unattended lake sites. Their lower value often keeps premiums down, though recovery coverage still matters.
One thing to keep in mind: owners sometimes undervalue their wheel house to save on premium. That backfires at claim time, because the policy pays only up to the stated value. Insure it for what it would actually cost to replace.
Common Questions About Fish House Insurance
Does my homeowners insurance cover my fish house? Sometimes, but not automatically. Many policies let you add it as a scheduled item, though coverage for ice recovery and off-premises losses is often limited or excluded.
Do I need a license and insurance for my fish house? Minnesota requires a license for all non-portable shelters, but insurance isn't legally required. The license keeps you compliant, while insurance protects your money.
Will insurance pay if my fish house goes through the ice? Only if your policy covers submersion and recovery. Specialty fish house policies commonly include it, while general policies frequently don't.
Is my fish house covered when I'm towing it? Your auto policy usually covers liability while towing. Damage to the house itself typically requires separate trailer, RV, or specialty coverage.
What happens if my gear gets stolen from my house on the lake? Theft coverage depends on your policy, and some require signs of forced entry. A photo inventory with serial numbers makes the claim far easier.
How much does fish house insurance cost in Minnesota? Specialty policies typically run $250 to $600 per year, depending on the house's value, deductible, and how you use it.
Making the Right Choice for Your Rig
The best fish house coverage isn't the cheapest one or the one bundled by default. It's the policy that matches how you actually use your house: where it sits, how often it moves, what's inside, and who joins you on the ice. Breakthrough recovery, heater fires, theft, and towing gaps are the claims that catch Minnesota owners off guard, so those are the areas to pressure-test first.
As the DNR puts it, the goal is shelters off by the deadlines and the ice free of litter. Good habits on the ice and a well-built policy work together.
Variant Insurance Group is an independent Minnesota agency, which means we can compare homeowners, RV, and specialty fish house options from multiple top-rated carriers side by side. Give us a call before your next season starts, and we'll help you find coverage that fits your rig, so a bad day on the ice doesn't become a bad year for your wallet.
On this page
Variant Insurance Group is a licensed independent insurance agency serving Minnesota families and businesses.
From our office in Maple Plain, our team works with many of Minnesota's top-rated carriers so your home, auto, life, and business coverage fits your real needs. We serve families and businesses across Minnesota.

About the Author
Charlie Brookins
Founder & Agent/Owner, Variant Insurance Group
I'm Charlie Brookins, founder and owner of Variant Insurance Group. I built this agency on one idea: local people and businesses deserve honest advice and coverage that fits their real life. As an independent agent in Maple Plain, I shop many of Minnesota's top-rated carriers to find the right protection for your home, auto, life, and business, and I stay with you through every claim and change. My goal is simple: give you straight answers and coverage you can trust.
One agent, many carriers
We represent many top-rated insurance companies. You get more coverage choices, better pricing, and one point of contact for every policy you own.
01
We shop as your life changes
04
New home, new vehicle, or a growing business? We re-shop your coverage across carriers so your protection keeps pace and your rate stays fair.

Personal Insurance
Coverage for your home, auto, and life
Protection for the people and things that matter most, shopped across Minnesota's top-rated carriers.
Auto Insurance
Coverage for your car, truck, or SUV. We compare carriers to protect you on the road at a fair price.
Home Insurance
Protection for your house, your belongings, and your liability. We match you with the right coverage for your home.
Life Insurance
Support for the people who depend on you. We help you compare term and whole life options that fit your budget.
Umbrella Insurance
Extra liability protection above your home and auto limits. A strong safety net for your family and your assets.
Renters Insurance
Coverage for your belongings and liability in a rented home or apartment. Affordable protection with quick setup.
Recreational Vehicle Insurance
Coverage for boats, motorcycles, ATVs, and campers. Enjoy the season with the right protection in place.
One agent, many carriers
We represent many top-rated insurance companies. You get more coverage choices, better pricing, and one point of contact for every policy you own.
01
We shop as your life changes
04
New home, new vehicle, or a growing business? We re-shop your coverage across carriers so your protection keeps pace and your rate stays fair.

Business Insurance
Coverage that protects what you have built
Liability, property, auto, and more, shopped across Minnesota's top-rated commercial carriers.
Workers Compensation
Coverage for employee injuries and lost wages. We help Minnesota employers meet state rules and protect their crew.
Commercial General Liability
Protection against third-party injury and property damage claims. Core coverage for most Minnesota businesses.
Commercial Property
Coverage for your building, equipment, and inventory. We protect the physical assets your business depends on.
Commercial Auto
Coverage for vehicles your business owns and drives. We match trucks, vans, and fleets with the right protection.
Commercial Umbrella
Extra liability limits above your other business policies. Added protection for larger claims and contracts.
Commercial Professional Liability
Coverage for your building, equipment, and inventory. We protect the physical assets your business depends on.
One agent, many carriers
We represent many top-rated insurance companies. You get more coverage choices, better pricing, and one point of contact for every policy you own.
01
We shop as your life changes
04
New home, new vehicle, or a growing business? We re-shop your coverage across carriers so your protection keeps pace and your rate stays fair.
Industries we serve
Coverage built for your industry

Contractor Insurance
Coverage for Minnesota contractors and the trades — general liability, tools and equipment, property, and workers comp. Protection for the job site and the crew.

Apartment Complex Insurance
Your income depends on the housing you provide, and wind, fire, or flood can interrupt it. Apartment Complex Insurance helps protect your property, your liability if a tenant or worker is injured, and your personal assets.

Brewery Insurance
You have pictured this brewery for years. Whether you just make great beer or serve food and merchandise too, Variant helps Minnesota breweries find the right coverage, from startups to major production facilities.


Our carrier bench
We shop these carriers so you don't have to


Plus specialty market access through Burns & Wilcox, CRC Group, Amwins, RPS and US Assure.
One agent, many carriers
We represent many top-rated insurance companies. You get more coverage choices, better pricing, and one point of contact for every policy you own.
01
We shop as your life changes
04
New home, new vehicle, or a growing business? We re-shop your coverage across carriers so your protection keeps pace and your rate stays fair.
Four steps, one real person from start to finish.
30 seconds — name, email, phone. Or just call. We’ll ask the right questions from there.
4
We stay in your corner
In their words
What our clients say
Frequently asked questions
Your insurance questions, answered
These are the questions Minnesota families and businesses ask us most. If you don't see yours here, call or message us — a real local agent is glad to help.
What does an independent insurance agency do?
An independent agency represents many insurance companies instead of just one. We shop your coverage across those carriers and compare protection and price for you.
That means more choices and one local team for every policy. You get honest guidance and a single point of contact you can trust.
How do you find me the best rate?
We start with your details and what you need to protect. Then we compare quotes from many top-rated carriers side by side.
We explain the coverage and the cost in plain terms, so the choice is clear. As your life changes, we re-shop your policies to keep your rate fair.
Can you handle both my personal and business insurance
Yes. We cover your home, auto, and life along with your workers comp, commercial property, and commercial auto.
One team manages it all, so you make one call for every policy. That saves you time and keeps your coverage consistent.
What should I do if I need to file a claim?
Call us or contact your carrier as soon as it is safe to do so. Gather photos, notes, and any details about what happened.
Our local team walks you through each step and follows up with the carrier. We stay in your corner until the claim is resolved.
Which areas do you serve?
Our office is in Maple Plain, Minnesota, and we serve families and businesses across the state. You can visit us, call, or email.
We know the local area and the coverage Minnesota requires. [CONFIRM: list any additional licensed states.]
How do I get started?
Request a quote online or call 763-333-2533. Share a few details and we take it from there.
We shop your coverage, compare your options, and explain what fits. There is no pressure and no obligation to buy.
One agent, many carriers
We represent many top-rated insurance companies. You get more coverage choices, better pricing, and one point of contact for every policy you own.
01
We shop as your life changes
04
New home, new vehicle, or a growing business? We re-shop your coverage across carriers so your protection keeps pace and your rate stays fair.

Named an Auto-Owners Sapphire Agency — a distinction reserved for a select group of the carrier's top-performing independent agencies.
From our blog
Insurance tips for Minnesota
Practical guides on coverage for your home, auto, and business.